How to Create a Long-Term Savings Plan for Big Life Goals
If you have ever dreamed about buying a home, starting a business, retiring comfortably, or moving abroad, you already know those goals require serious money. The truth is, big life goals do not happen by accident. They happen with a clear, long-term savings plan. I have learned this through trial and error, and in this guide, I will show you exactly how to build one that actually works.
Step 1, Clearly Define Your Financial Goal
You cannot save effectively for something that is vague. Saying, I want to buy a house someday, is not enough. You need numbers and specifics.
When I decided to save for a property, the first thing I did was research realistic prices in the area I wanted. That gave me a target instead of a dream.
Ask yourself:
- What exactly am I saving for?
- How much will it cost today?
- How much might it cost in the future?
Be specific. Instead of saying retirement, say I want 500,000 dollars by age 60. Instead of saying travel, say I want 20,000 dollars in five years for relocation.
It may feel uncomfortable to look at large numbers, but clarity is powerful.
Also consider inflation. If your goal is 10 years away, prices will likely rise. Add a buffer to protect yourself from future increases.
Step 2, Determine Your Timeline
Your timeline determines your strategy. Saving for a goal in three years is very different from saving for something 25 years away.
When I first calculated my timeline, I realized I was either being too optimistic or too relaxed. Both extremes can hurt your progress.
Here is how to think about time:
- Short term goals, 1 to 3 years
- Medium term goals, 3 to 7 years
- Long term goals, 10 years or more
The longer your timeline, the more you can take advantage of compound growth through investments. Shorter timelines require safer options.
If your goal is long term, you can tolerate small market ups and downs. If it is short term, protecting your capital becomes more important.
Be realistic. If you set an aggressive deadline that does not match your income, you may feel discouraged and quit.
Step 3, Calculate How Much You Need to Save Monthly
This step turns your dream into a real plan. Once you know your total goal and timeline, you can break it down into monthly contributions.
For example, if you need 60,000 dollars in five years, that equals 1,000 dollars per month, assuming no investment growth. Seeing this number helps you understand whether your goal is realistic.
To calculate properly:
- Divide your total target by the number of months until your deadline
- Adjust for expected investment returns if applicable
- Add a small safety margin
When I first did this, I realized my monthly target was too high for my income. Instead of giving up, I adjusted my timeline and increased my income.
That is the beauty of clear numbers, they give you options.
Step 4, Create a Dedicated Savings System
Saving works best when it is automatic. If you rely on willpower, you will struggle.
I used to transfer money manually every month. Sometimes I forgot, sometimes I spent it first. Automation changed everything.
Here is what helped me:
- Open a separate savings account
- Label it with your goal name
- Set up automatic monthly transfers
- Avoid mixing it with daily spending money
If your goal is long term, consider an investment account instead of just a regular savings account.
A dedicated system creates separation. When money is out of sight, it is less tempting to spend.
Step 5, Choose the Right Savings and Investment Vehicles
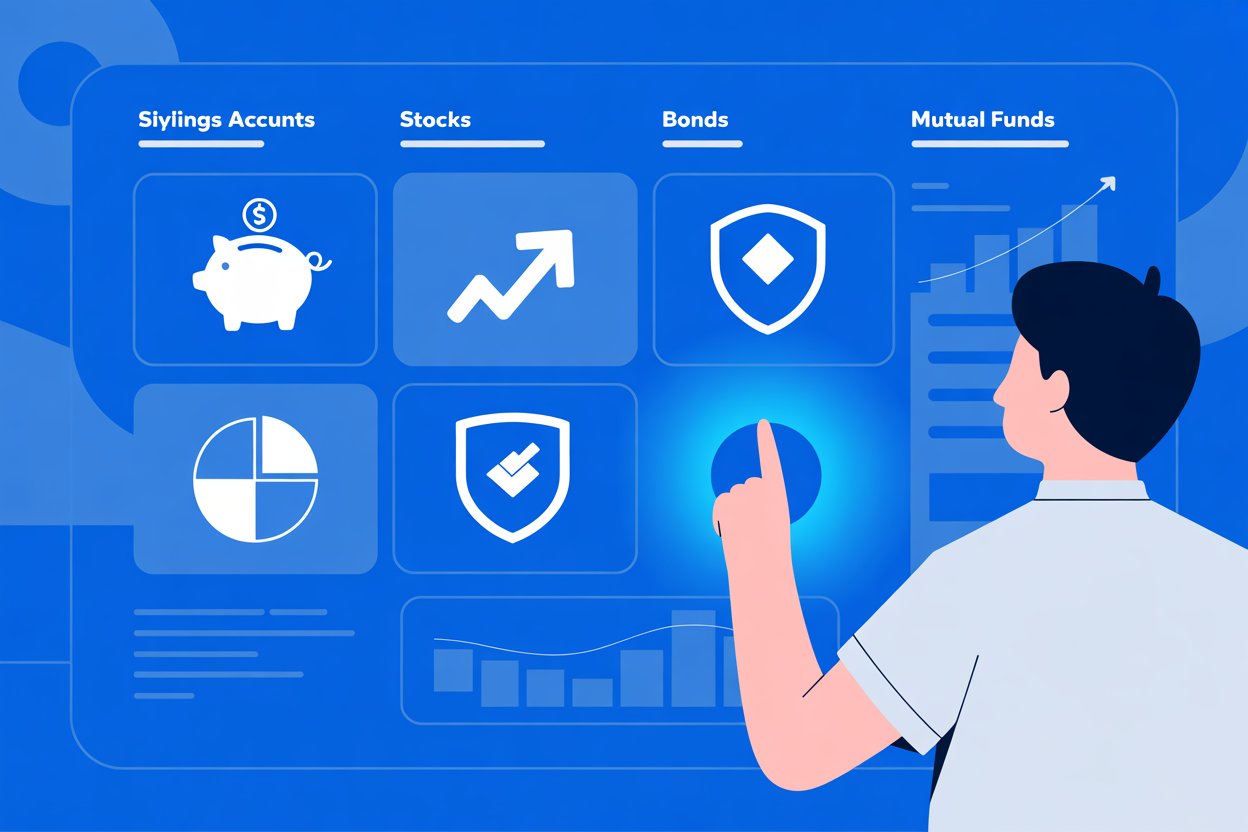
Not all savings methods are equal. The right choice depends on your timeline and risk tolerance.
For short term goals, safer options are better. For long term goals, growth matters more.
Common options include:
- High yield savings accounts
- Fixed deposits
- Mutual funds
- Exchange traded funds
- Retirement accounts
- Government bonds
When I started investing for long term goals, I was nervous. Market fluctuations felt scary. Over time, I learned that patience is key.
Diversification is important. Instead of putting everything in one place, spread your money across different assets. This reduces risk.
Always match your investment choice to your timeline. Do not invest money you will need next year in high risk assets.
Step 6, Build an Emergency Fund First
Before focusing heavily on big life goals, build an emergency fund. I learned this lesson after an unexpected expense forced me to withdraw from my savings.
An emergency fund protects your long-term plan from disruption.
Aim for:
- Three to six months of living expenses
- Stored in a safe, easily accessible account
- Separate from your goal savings
Without this cushion, one crisis can undo years of discipline.
Think of your emergency fund as financial insurance. It gives you peace of mind and stability.
Step 7, Increase Your Income to Accelerate Savings
Sometimes cutting expenses is not enough. Increasing income can speed up your progress dramatically.
When I wanted to reach my savings target faster, I focused on earning more rather than just spending less.
You can:
- Take on freelance work
- Start a small side business
- Negotiate a salary increase
- Develop high income skills
- Invest in certifications
Extra income does not have to be permanent. Even a temporary boost can help you reach important milestones sooner.
Growing income also builds confidence. You realize you have more control than you thought.
Step 8, Reduce Expenses Strategically Without Feeling Deprived
Cutting every enjoyable expense is not sustainable. I tried extreme budgeting once, and it only lasted a few months.
Instead, focus on intentional spending.
Look at your expenses and ask:
- Does this add real value to my life?
- Can I find a cheaper alternative?
- Is this purchase aligned with my long-term goal?
Small changes can make a big difference over time. Cooking at home more often, reducing subscriptions, or renegotiating bills can free up money.
The key is balance. You are building a future, not punishing yourself.
Step 9, Protect Your Savings from Inflation and Risk
Inflation slowly reduces purchasing power. If your money sits in a low interest account for 20 years, it may lose value.
This is why long-term goals often require investment growth.
Ways to protect your savings include:
- Investing in diversified funds
- Holding assets that historically outpace inflation
- Reviewing your portfolio annually
- Adjusting your strategy as your timeline shortens
Risk management is just as important. Do not chase high returns without understanding the downside.
As your goal approaches, gradually move money into safer assets to protect what you have built.
Step 10, Track Progress and Adjust Regularly
A long-term savings plan is not set once and forgotten. Life changes, income changes, goals evolve.
I review my financial goals at least once a year. Sometimes I increase contributions, other times I adjust timelines.
Tracking helps you:
- Stay motivated
- Catch problems early
- Celebrate milestones
- Adapt to unexpected events
Use a spreadsheet or budgeting app to monitor progress. Watching the numbers grow can be incredibly motivating.
If you fall behind, do not panic. Adjust and continue. Consistency matters more than perfection.
What Qualifies as a Big Life Goal
Not every purchase needs a long-term savings plan. Big life goals usually require years of preparation and significant money.
Examples include:
- Buying a home
- Starting a business
- Paying for higher education
- Early retirement
- Relocating to another country
- Achieving financial independence
These goals change your life in a meaningful way. They deserve intentional planning.
When you treat your dreams seriously, your actions follow. Saving becomes purposeful, not random.
Final Thoughts
Creating a long-term savings plan is not complicated, but it requires discipline and clarity. I used to think big financial goals were only for high earners. That belief was wrong.
The real difference is planning and consistency.
Start small if you need to. Open a dedicated account. Define your goal clearly. Automate your contributions. Increase your income when possible.
Over time, small consistent actions compound into powerful results.
Your big life goals are not unrealistic. They simply require structure, patience, and commitment. When you build a solid long-term savings plan, you stop wishing and start building.